Why Public Liability Insurance Matters for Tasmanian Businesses
Running a business involves risks, even when you take every reasonable precaution. An unexpected accident involving a customer, visitor or member of the public can quickly turn an ordinary working day into a costly problem.
For business owners considering public liability insurance in Tasmania, understanding what their policy covers — and what it doesn’t — can make an important difference when something goes wrong.
Accidents Can Happen Anywhere
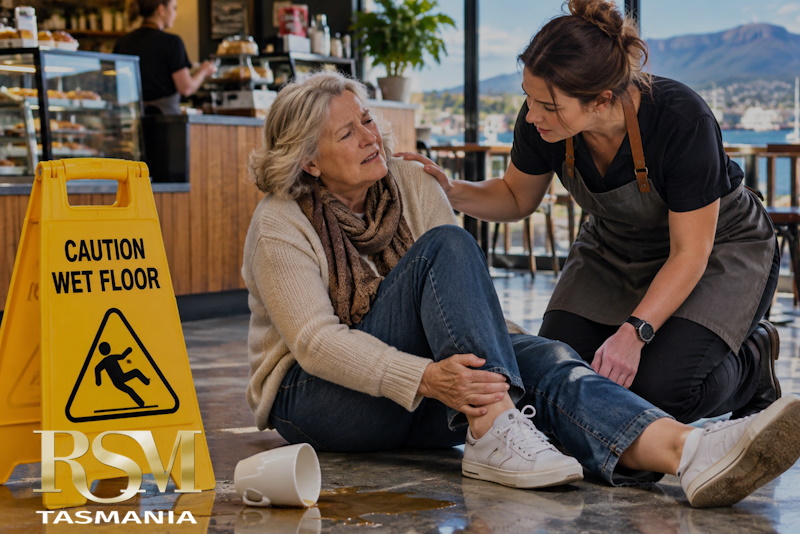
Imagine a customer slipping on a freshly cleaned floor in a Hobart café. Or a tradesperson accidentally damaging expensive flooring while carrying out renovations at a client’s property.
Perhaps a delivery driver accidentally damages a customer’s fence while unloading goods.
These are everyday situations that could lead to a claim against a business.
Even when appropriate safety precautions are in place, accidents can still happen. And when someone believes your business is responsible for their injury or damaged property, the resulting claim can become expensive.
What Does Public Liability Insurance Cover?
Public liability insurance is designed to protect businesses against certain claims involving third-party personal injury or property damage arising from their business activities.
Depending on the policy and circumstances, cover may include:
– Compensation for covered injuries suffered by customers or members of the public.
– Costs associated with accidental damage to someone else’s property.
– Legal defence costs relating to insured claims.
– Settlements or damages payable under the terms of the policy.
Importantly, public liability insurance does not cover every accident or business loss. Exclusions, conditions and policy limits apply.
For further information on your business insurance, you will find valuabe information HERE
It’s Not Just for Larger Businesses
It’s easy to assume public liability insurance is something only larger companies need.
However, small businesses, sole traders and home-based operators can also face claims.
A gardener working at a customer’s property, a mobile hairdresser visiting clients or a retailer welcoming customers into a shop may all encounter situations where public liability insurance becomes relevant.
The size of your business doesn’t necessarily determine the size of a potential claim.
Public Liability or Professional Indemnity?
These two types of insurance are sometimes confused, but they generally address different risks.
Public liability insurance typically responds to covered claims involving third-party injury or property damage.
Professional indemnity insurance, on the other hand, generally addresses claims arising from professional advice or services, such as allegations of negligence, errors or omissions.
Some businesses may need both, depending on the nature of their operations.
Is Your Business Properly Protected?
Every business is different. The insurance needs of a café, building contractor, consultant or retail shop will vary according to the work they perform and the risks they face.
It’s worth reviewing your insurance whenever your business activities change, particularly if you begin offering new services, working at different locations or employing additional staff.
At RSM Tasmania Insurance Brokers, we help Tasmanian businesses understand their risks and explore insurance options appropriate to their circumstances.
Because even a small accident can sometimes have very expensive consequences.
Remember, this article is general in nature and doesn’t take into account your specific objectives, financial situation, or needs. For advice tailored to your circumstances, have a chat with us at RSM Tasmania Insurance Brokers Hobart.
Talk to Roger Hosie and stay ahead with RSM Tasmania’s insights.
Call Now! (03) 6244 7854, or email .
You can also follow RSM Tasmania on Facebook and LinkedIn for regular business insights.
Click Here for more information specifically about workers compensation in Tasmania,
visit https://wcomptas.com.au/